
Transactions
This monthly spending plan guide starts with listing total income, then tracking every expense against it, the core practice behind learning to track income and expenses with confidence. Pocket Accountant helps freelancers and small business owners build monthly spending plans, comparing actual results with planned amounts and turning guesswork into a clear month-to-month view of where cash actually goes.
Key Takeaways
- A realistic spending plan shows exactly how much you earn and where every dollar goes each month.
- Track your actual spending for 30 days to identify patterns and find money you didn’t know you had.
- Separate fixed costs like rent from variable expenses to understand which spending you can adjust immediately.
- Review and adjust your plan monthly because your income and priorities shift—static plans become useless fast.

What Does It Mean To Build A Realistic Spending Plan?
A realistic spending plan starts as a written plan for spending money earned each month. Nothing fancy, no complicated math — just a clear picture of income against outflow. Skip that honesty step, and the whole plan collapses the first time a real bill shows up.
Numbers matter more than good intentions here. Comprehensive income and expense tracking gives a spending plan its foundation, turning guesswork into something grounded in actual cash movement. Without that tracking, a spending plan becomes a wish list rather than a working tool.
Is a monthly spending plan only for businesses?
No. Realistic monthly planning applies just as much to freelancers. Individuals managing personal money as it does to small business owners. A solo freelancer juggling irregular invoices faces the same core challenge as a shop owner: matching what comes in against what goes out.
How does a monthly spending plan fit into bigger financial planning?
This kind of planning rarely stands alone. It connects to a wider financial management picture that includes:
- Setting monthly or seasonal spending plans
- Preparing tax estimates ahead of deadlines
- Reconciling accounts against bank activity
- Generating reports that show where things stand
Together, these pieces turn a simple monthly plan into ongoing financial planning. One that draws on historical spending patterns to shape a more accurate forecast of what’s coming next.
How Do You Start Building Your Monthly Spending Plan?

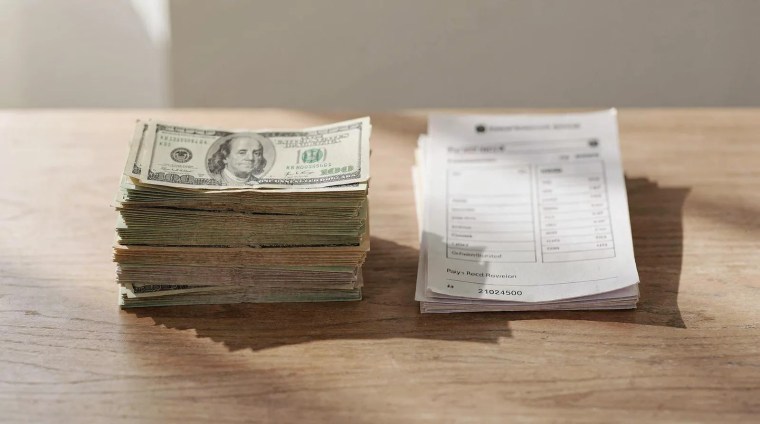
Two piles of paper hold the answer: bills and pay records. Gathering these documents first shows freelancers and small business owners exactly what money comes in and what goes out each month, before any planning begins.
Once those documents sit on the table, the next move is listing every expense with its exact amount. Rent, utilities, subscriptions, loan payments. Each one gets written down, even the small recurring charges that slip through the cracks. This step turns vague guesses about spending into a concrete, line-by-line record.
What should go into a monthly spending plan list?
A solid list includes fixed costs like rent alongside variable ones like groceries or fuel. This is where a variable income spending plan matters most for freelancers, who should note irregular earnings since income often shifts month to month. Anyone working to create a personal spending plan needs to capture every dollar’s movement, not just the predictable ones.
Keeping income, expenses, transactions, and journal entries together in a single view matters here. Scattered records across notebooks, spreadsheets, and bank apps make it easy to miss a bill or double-count a deposit. From there, building a monthly plan means setting target amounts by category and checking actual results against those numbers over time — comparing this month’s spending to historical patterns and adjusting the forecast for the next one.
Does automation help with spending-plan accuracy?
Yes. Bank transactions imported automatically arrive ready for review, which cuts down on the manual entry errors that leave gaps in a spending plan.
How Do You Keep Your Spending Plan Realistic Over Time?

A realistic spending plan framework rests on real numbers, not guesses. Profit and loss statements, balance sheets, cash flow reports, and aging reports reveal historical performance that anchors future planning in what actually happened, not what someone hoped would happen. That distinction matters. A plan built on wishful thinking often fails. One based on actual patterns is more likely to succeed but still requires regular review.
Raw data alone doesn’t help much if nobody understands what it means. That’s where asking a direct question — how much should go toward taxes, or where a category of spending is drifting — turns spreadsheet clutter into an answer someone can act on immediately.
Why do spending plans drift off track so easily?
Small business owners and freelancers often lose track of categories that quietly grow month over month. AI-assisted categorization helps by interpreting historical financial data so those patterns surface instead of hiding in a miscellaneous bucket.
How do accurate records support better forecasting?
Understanding spending plan vs forecast is simple: a plan sets the targets, a forecast projects what’s likely based on the data feeding it. Capturing expenses through receipt scanning the moment they happen keeps historical records accurate, and accurate records make every future plan more dependable.
Consider the difference between two approaches:
- Apartment-percentage tax guesses based on rough assumptions
- Tax estimates built from what the business genuinely earned and spent during the year
The second approach produces a far more realistic forecast. It reflects actual operations rather than a generic rule of thumb.
FAQ
Is a monthly spending plan only for businesses?
No. Realistic monthly planning applies just as much to freelancers. Individuals managing personal money as it does to small business owners. Matching income against outflow is the same core challenge for everyone.
How does this planning fit into bigger financial management?
This kind of planning connects to setting monthly or seasonal spending plans, preparing tax estimates, reconciling accounts against bank activity, and generating reports, turning a simple monthly plan into ongoing financial planning based on historical spending patterns.
Does automation help with spending-plan accuracy?
Yes. Bank transactions imported automatically reduce manual entry and missed items, keeping records current and helping build a more accurate, month-to-month spending picture.
Conclusion

In closing, building a realistic monthly spending plan isn’t about perfection—it’s about understanding where your money actually goes and making intentional choices from there. Once you’ve tracked your income, listed your expenses, and set your targets, the real work is reviewing and adjusting as life happens. That’s where the clarity kicks in: when you can see your numbers clearly, spot patterns, and answer the questions that matter to your business, you’re not just planning anymore. You’re in control.


